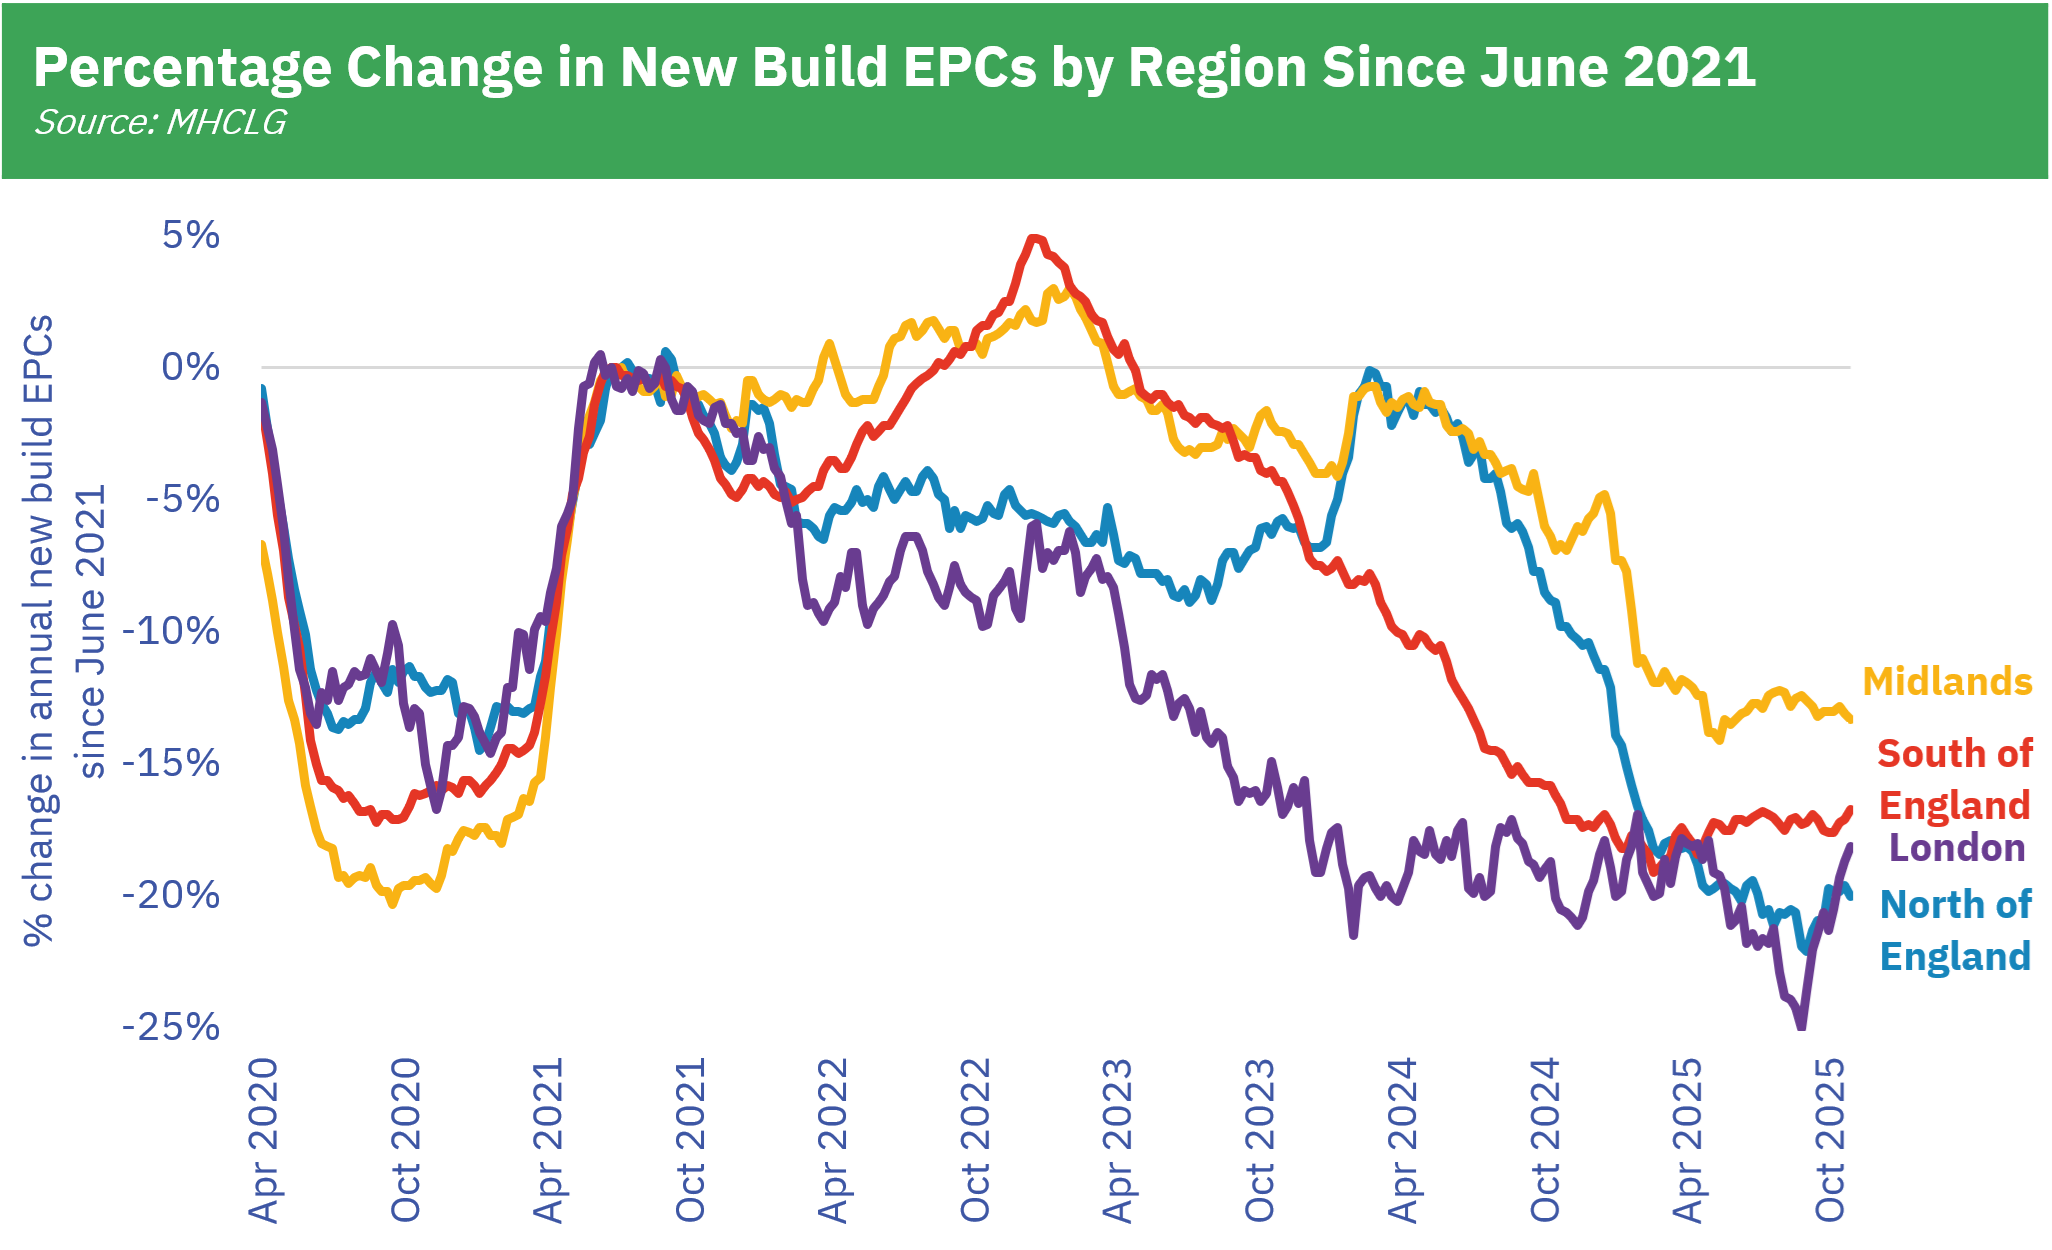
DATA: ONS estimated monthly GDP rose 1.1% in year to Sep 2025
The data shows monthly GDP was 5.4% above its pre-pandemic peak in January 2020.
DATA: ONS published labour market overview
They report “The early estimate of payrolled employees for October 2025 decreased by 180,000 (0.6%) on the year” and “The UK unemployment rate for people aged 16 years and over was estimated at 5.0% in July to September 2025”. They also report “Annual growth in employees’ average earnings in Great Britain for regular earnings (excluding bonuses) was 4.6%, and for total earnings (including bonuses) was 4.8% in July to September 2025”.
DATA: BoE published construction output data for Q3 2025
They report “At the sector level, four out of the nine sectors grew in Quarter 3 2025; the main positive contributor to the increase was private housing repair and maintenance, which grew by 2.9%; the main negative contributor was private new housing, which fell by 1.9%”.
DATA: UKF published mortgage arrears and possessions for Q3 2025
They report “The number of homeowner mortgages in arrears fell by four per cent in Q3 2025 compared to the previous quarter” and “The number of buy-to-let (BTL) mortgages in arrears fell by eight per cent compared with the previous quarter”. They also report “1,390 homeowner mortgaged properties were taken into possession in the third quarter of 2025, 4 per cent greater than in the previous quarter” and “900 buy-to-let mortgaged properties were taken into possession in the third quarter of 2025, 14 per cent greater than in the previous quarter”.
DATA: MoJ published mortgage and landlord possessions for Q3 2025
They report “Mortgage claims have decreased while all other mortgage actions have increased” and “Landlord repossessions have increased while all other landlord possession actions have decreased”.
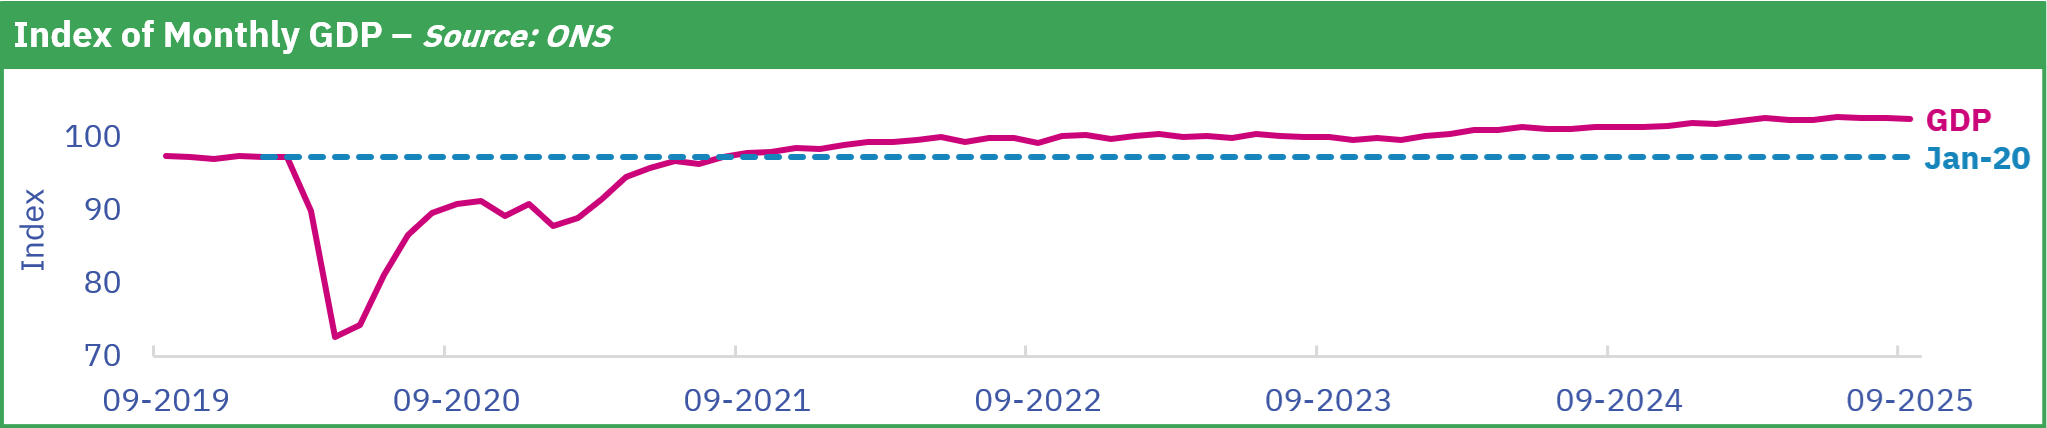
DATA: ONS published Dataloft rental affordability data for Aug 2025
The latest data on the actual cost of private rents as a proportion of the renter’s income decreased to 29.5% in October.
DATA: NHBC published housebuilding activity data for Q3 2025
They report “30,643 new homes registered in Q3 2025, 8% up on Q3 2024” and “26,427 new homes completed in Q3 2025, 6% down on Q3 2024”. Please note that these figures only account for around 60% of actual completions.
DATA: MHCLG published social housing lettings in England, 2024/25
They report “In 2024/25, the North East had the highest rate of churn in England – the proportion of existing social stock that was relet – at 6.6%, whilst London had the lowest at 2.7%” and “The median weekly rent for new social housing lettings in 2024/25 was £113 up from £103 in 2023/24, an increase of 10%”.
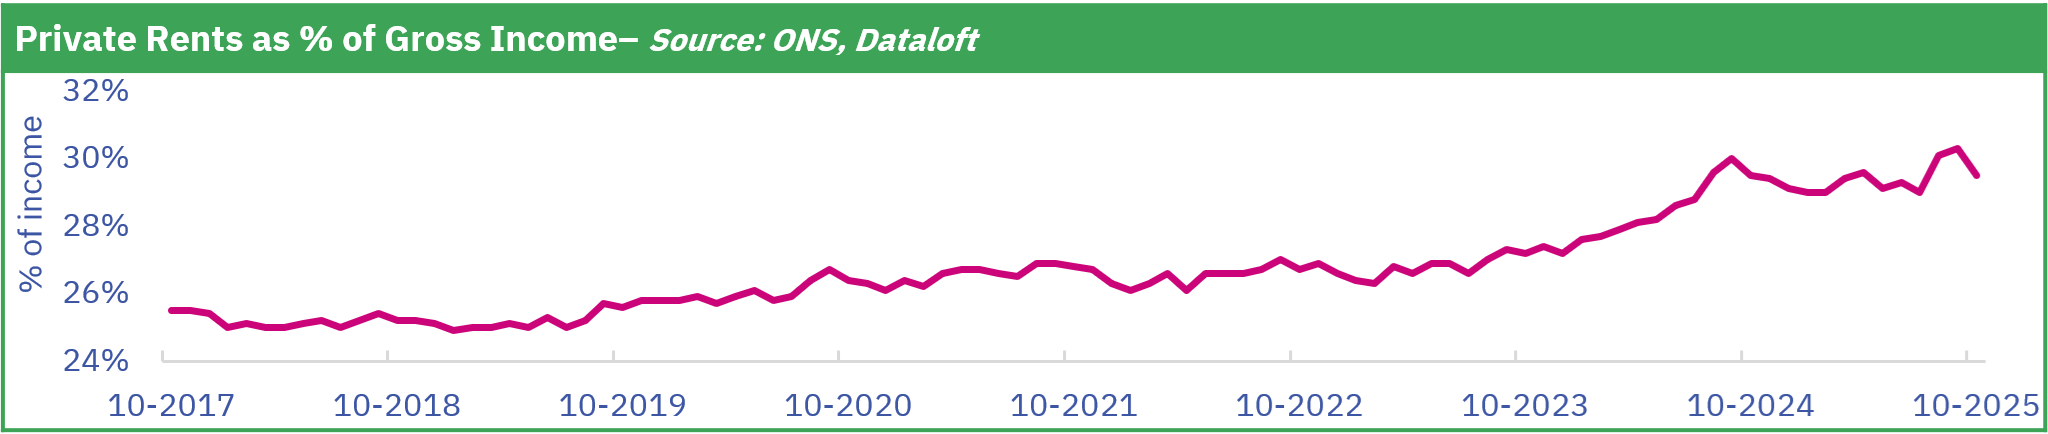
DATA: Financial Market Expectations For BoE’s Bank Rate
The chart provides a summary for the expected future level of Bank Rate based on daily data. The One Year figure was 3.33% on the 12th Nov compared to 3.43% on the 5th Nov.
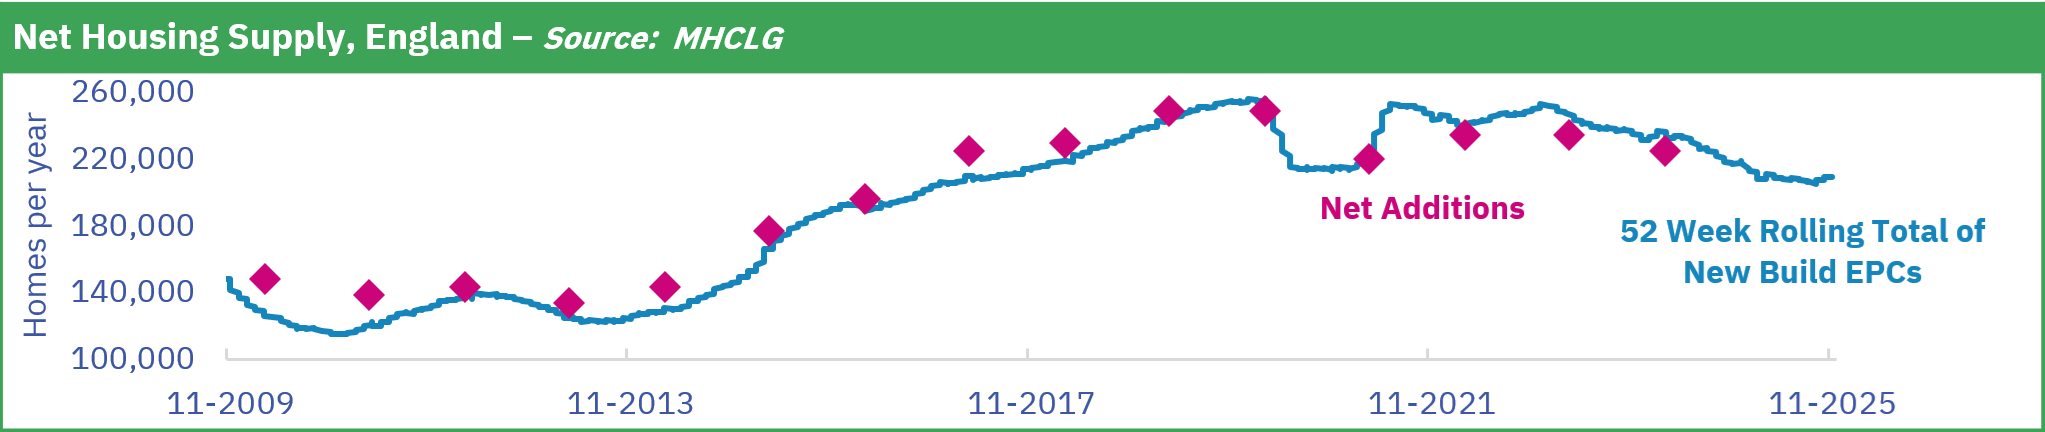
DATA: New Build Energy Performance Certificates, England
This chart provides a summary of the number of EPCs on new build properties, a useful leading indicator for net additions. The 52-week rolling total was 209,430 for the week commencing 3rd Nov, slightly higher than the 209,111 total for the previous week.
POLICY: MHCLG published Renters’ Rights Act 2025 roadmap
From the 1st May 2026, they will: “abolish section 21 ‘no fault’ evictions”, “introduce Assured Periodic Tenancies”, “reform possession grounds”, “limit rent increases to once a year”, “ban rental bidding and rent in advance”, “make it illegal to discriminate against renters who have children or receive benefits”, “require landlords in the PRS to consider tenant requests to rent with a pet” and “strengthen both local council enforcement and rent repayment orders”. Phase 2 in late 2026 will see the rollout of the landlord database and introduction of the PRS Landlord Ombudsman. Phase 3 will introduce a new Decent Homes Standard and it is expected to be brought into force in either 2035 or 2037.
POLICY: FCA CEO speech on mortgage market of tomorrow
He states “The current mortgage market is healthy” and suggests “OpenFinance and AI will transform the mortgage market”.
REPORT: RICS published residential market survey for October 2025
They report “Headline indicators tracking sales market activity remain in negative territory” and “House prices continue to face modest downward pressure at the national level”. They also report the “Subdued backdrop [is] expected to persist over coming months”.
REPORT: Crisis published The Homelessness Monitor: England 2025
They report “The total number of households experiencing the worst forms of homelessness (‘core’ homelessness, which includes rough sleeping, sofa surfing, and staying in hostels, refuges, or unsuitable temporary accommodation) now stands at just under 300,000” and “If current policies continue, core homelessness will continue to rise”.
REPORT: University of Warwick reported on where to build 1.5m homes
Using Rightmove data on searches and listings, they have mapped “where and how these homes should be built to meet actual demand”. They conclude “Great Britain has built too little densification while building too many new “rural developments and urban extensions relative to what is demanded” – though one of their outputs (Gap per km2) looks rather like a population density map.
REPORT: BPF reported on the build-to-rent market in Q3 2025
They report “Nationally, the number of units under construction fell by 13% in Q3 2025 compared to Q3 2024 as the number of starts has failed to keep pace with completions” and “The number of units under construction has fallen sharply across the country, albeit more sharply in London (29%) than in the regions (5%)”.
REPORT: BPF reported on boosting development viability
The report looks at the viability challenges and “examines the combination of market, tax and regulatory pressures driving this issue, including higher interest rates, rising construction costs and delays linked to the Building Safety Regulator”.
REPORT: Construction Plant-hire Association on infrastructure plans
They report “Britain’s construction engine is stalling under the combined strain of skills shortages, weak investment and chronic delivery delays”.
REPORT: Knight Frank published UK student housing outlook
They report “While historic growth has been underpinned by a persistent demand-supply imbalance, forward-looking factors, such as geopolitical risk, affordability and occupancy challenges, and the ‘mid-market’ opportunity will shape performance in the next cycle”.
REPORT: Savills reported on Welsh housing market and supply
They report “Price growth and activity robust in 2025, but development outlook very weak”.
BLOG: Bank Underground on the drivers of house price growth
They report “measures of real household income explain much of their variation over time” and “The rise in mortgage rates during the recent tightening cycle is estimated to have kept house prices nearly 10% lower than had interest rates not moved, with some of this effect offset by real income growth”.
BLOG: IPPR on a fairer and proportional property tax
They recommend the chancellor should “Raise rates on higher council tax bands”, “Lower rates on lower council tax bands”, and “Raise the foreign buyer surcharge”.
CORPORATE: Taylor Wimpey published Trading Statement
They report “Reflecting current uncertainty in the housing market ahead of the November Budget, we continue to experience softer market conditions in the second half of the year to date. As a result, for the period from 30 June to 9 November 2025 the net private sales rate per outlet per week was 0.63 (2024: 0.71), with a cancellation rate of 17% (2024: 17%). Excluding the impact of bulk deals, we achieved a net private sales rate of 0.61 (2024: 0.68) in the period.”
CORPORATE: Persimmon published Trading Statement
They report “Our sales rate increased to 0.76 net private sales per outlet per week, or 0.63 when excluding bulk sales, representing an increase of 3% on the prior year (2024: 0.61)” and “This progress has been achieved despite some softening in the market since the summer, with consumer confidence affected by ongoing uncertainties including the upcoming Government budget”.
CORPORATE: MJ Gleeson published AGM Trading Update
They report “Gleeson Homes’ open market net reservation rates for the eight weeks to 7 November 2025, increased by 22% to 0.50 per site per week (0.92 including bulk reservations), from the 0.41 per site (0.46 including bulk reservations) during the same period last year” and “Demand for new homes remains subdued, but steady, with buyers lacking confidence in the current economic environment”.
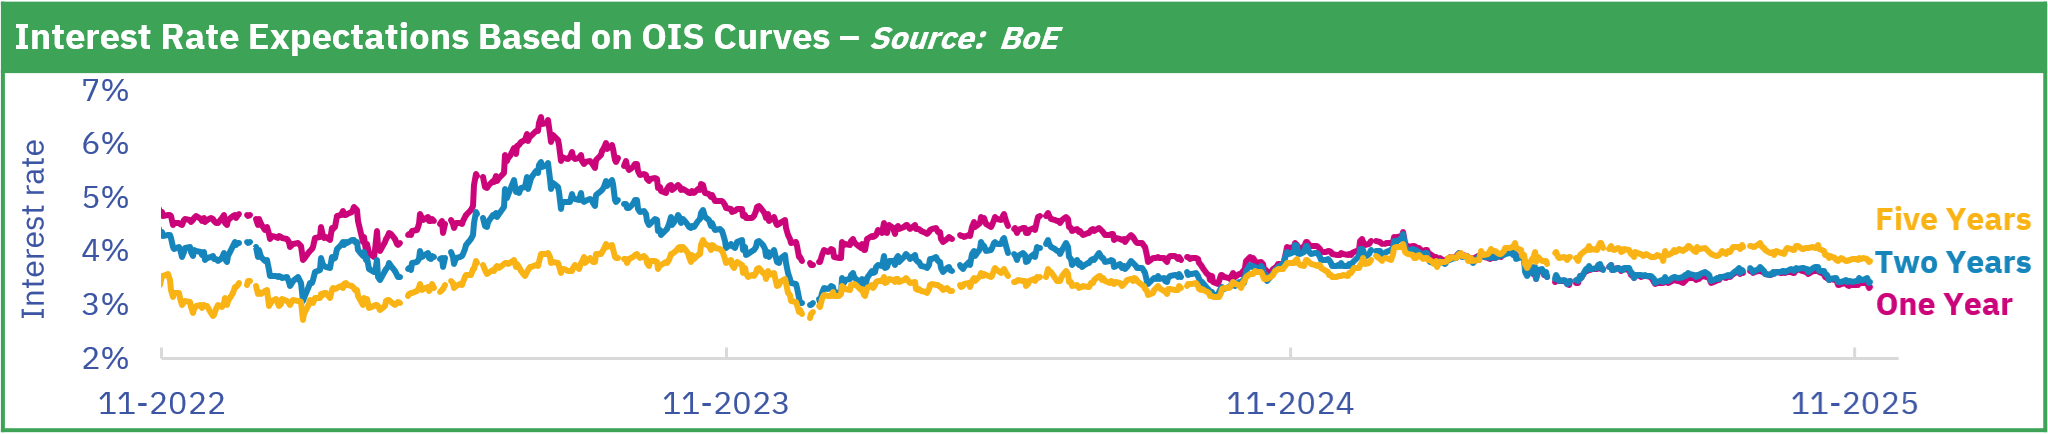
Chart of the Week
There are some signs that new build completions may have hit the bottom – at least for now. Recent MHCLG and NHBC data, despite their flaws, shows an improvement and my tracking of the weekly EPC data has shown small increases in the rolling annual total over the last eight weeks or so. Looking more closely at the regional data below and it appears to be a combination of bigger rebounds in London and the North of England along with a more gradual improvement in the South of England. While there’s a decent probability that the worst of the declines are over, we’re some way off declaring the start of the recovery.