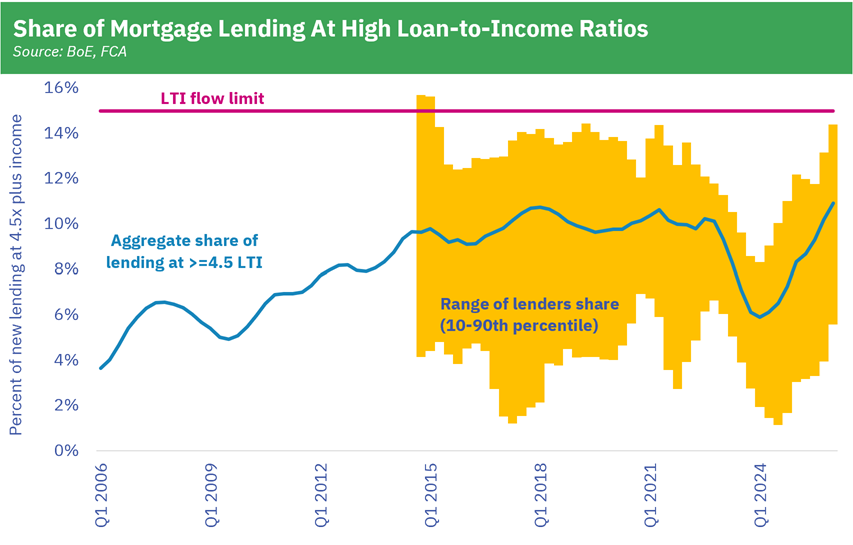
DATA: Lloyds reported UK house prices rose 0.6% in year to Jun 2026
They report(PDF) the rebranded Halifax index was 0.2% higher than the previous month and the annual rate increased slightly, from 0.5% to 0.6%. They also report “Northern Ireland continues to record the UK’s strongest annual growth at +7.4%” while “the East led declines, with prices down -2.0 % year -on -year to £ 381,654”.
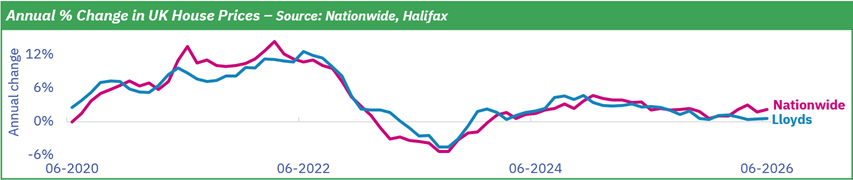
DATA: BoE published quoted mortgage rates for Jun 2026
They report the average rate on a two-year fixed-rate mortgage at 75% loan-to-value fell slightly to 4.81% in June, from 4.92% the previous month. The two-year variable rate and revert-to-rate rates were unchanged, at 4.14% and 6.60% respectively.
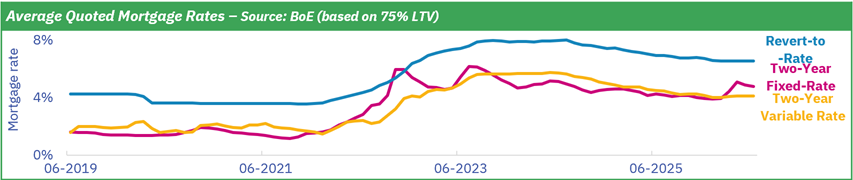
DATA: Financial Market Expectations For BoE’s Bank Rate
The chart provides a summary for the expected future level of Bank Rate based on daily data. The One Year figure was 4.25% on the 8th Jul, up from 4.00% on the 1st Jul.
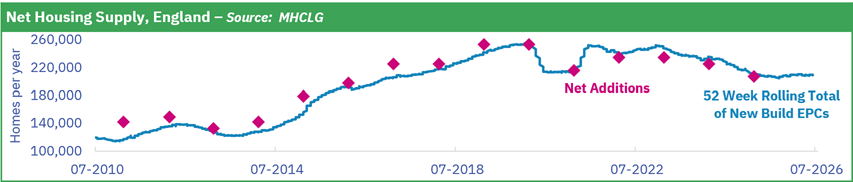
DATA: New Build Energy Performance Certificates, England
This chart provides a summary of the number of EPCs on new build properties, a useful leading indicator for net additions. The 52-week rolling total was 209,464 for the week commencing 29th Jun, slightly lower than the 209,719 total for the previous week.
POLICY: MHCLG expanded cladding funding to lower-rise buildings
“The new funding for under 11 metre buildings will be part of the existing Cladding Safety Scheme, with support prioritised for those facing the greatest risk.”
POLICY: Cabinet Office launched Airbnb data-sharing partnership
“People illegally subletting social housing will be identified and may be removed from the property, following a new, innovative data-sharing partnership between the Cabinet Office and Airbnb”. They also report “It is estimated that 5,800 social homes are suspected of being illegally sublet on short-term rental platforms in England”.
POLICY: Scottish Gov launched mansion tax consultation
They are seeking views “on plans to introduce two new council tax bands for properties worth more than £1 million and £2 million respectively” based on 1st April 2026 values.
REPORT: BoE published Financial Stability Report
They report “A little over 5 million households are projected to see their repayments increase by the end of 2028, compared to nearly 4 million at the time of the December FSR” and “Nearly 750,000 households that are paying less than 3% interest will be rolling off fixes in 2026 and will see an average increase of £170 per month in repayments”. See Chart of the Week for more on their analysis of high loan-to-income multiple lending.
REPORT(PDF): RICS published Residential Market Survey for Jun 2026
They report “Measures of buyer demand and newly agreed sales still negative, albeit marginally less so than before” and “Headline house price indicator largely stable in recent months, although this remains consistent with a modest degree of downward pressure”, while “Near-term sales expectations turn somewhat less negative, but are yet to signal a genuine turnaround”.
REPORT: MHCLG published English Housing Survey report & factsheets
They include “perceptions and impacts of housing quality”, “weather resilience in housing – fact sheet”, “housing and place – fact sheet”, “homelessness, hidden households and temporary accommodation – fact sheet”, and “shared owners – fact sheet”.
REPORT: MHCLG on their remediation programme insurance survey
They report “The average premium rate was 0.14% for buildings where cladding or other external defects were still present (992 buildings), compared with 0.09% where cladding or other external defects were not present, or where information on their presence was unavailable (1,037 buildings)”.
REPORT: London Assembly published Affordable Housing Monitor 2026
They report “The AHP 2021-26 achieved 14,335 affordable home starts by March 2026, against a target of 17,800 to 19,000” and “73 per cent of homes funded by the AHP 2016-23 have been completed” which “leaves 32,081 homes that have been started but not yet completed”.
REPORT: Shelter and Savills on reducing Housing Revenue Account debt
They report “HRA debt has risen to approximately £31.8bn, significantly inhibiting the ability of authorities to invest in both existing stock and new homes” and “Debt reduction could unlock significant new supply of social rent homes” as “Per £1bn of debt written off, around 8,900 new social rent homes could be delivered”.
REPORT(PDF): Crisis reported on LHA rates and homelessness
They report that Local Housing Allowance (LHA) “now covers the rent on fewer than 2% of privately advertised homes across Great Britain” and the freeze in LHA “is forcing households to cut back and go without essentials”, “driving people into homelessness”, and “trapping people in temporary accommodation”.
REPORT: CPS reported on social housing subsidies
They report the “commitment to spending £39bn on new social housing will add to the taxpayer’s burden and may only deliver between 14,335 and 15,494 homes per year”.
REPORT: Savills reported on the affordable housing investment market
They report “Registered Providers are feeling more positive in 2026, despite challenging market conditions” and “Section 106 demand has improved, with some major RPs re-entering the market over the last year” but “challenges remain across both funding and development”.
REPORT: Public First on restoring the housing ladder
The report for Yorkshire Building Society finds “Britain still believes in the housing ladder” but “the housing ladder has become not only harder to get onto, but more difficult to move through”. Their priorities include “Unlocking transactions and strengthening chains”, “Expanding the supply of suitable homes”, and “Building stronger foundations for a more responsive market”.
REPORT: Fabians reported on homeownership & first-time buyers
The report provides a poor evidence base including undercounting data on first-time buyers to suggest “a targeted deposit loan scheme for first-time buyers”, changes to shared ownership and improvements to “new home quality and consumer outcomes”.
REPORT: CIOB reported on More Homes Scotland
“Drawing on lessons from Canada, this paper highlights the importance of evaluating and learning from the impacts policy and public spending have” when asking “How will we know if More Homes Scotland is working?”.
REPORT: JLL reported on London’s missing middle
They report “a structural crisis in the housing market is quietly eroding that foundation, pricing out the very workforce that keeps the city running” and suggest “Site viability reform”, “Professionalising the HMO sector”, and “Compact studio models” to “unlock genuinely affordable rental supply for the squeezed middle”.
REPORT: UCL on coordinated reform for the UK
The report proposes “A costed, fully-funded, five-year programme that sequences welfare and tax reforms to reduce the cost of living and offset increases in taxation” including phasing in “a new Property Tax, at 1% of the value of the property, over three years, while Council Tax and Stamp Duty are phased out over the same time frame”.
REPORT: LPDF & Lichfields on needing a more efficient planning process
They report “the planning process has become increasingly unwieldy for applicants and overly contentious” and suggest “Measuring what matters”, “Getting the culture right”, and “Applying the principle of proportionality”.
BLOG: Bank Underground on credit constraints and housing market access
On deposit constraints and homeownership, they “previously demonstrated that this easing of deposit constraints generated a clear increase in local spending” and “In a recent paper, we show that lowering this constraint increases FTB home purchases, particularly among households without access to external financial support for their deposit”.
NEWS: NHF reported on rural affordable homes
They warn “An estimated 32,000 new affordable homes, and half of all new affordable homes in rural areas could be lost over the next decade, if new proposed changes to planning rules are brought into effect”.
NEWS: Rightmove reported on new build development listings
They report “the number of new build housing developments coming to market is at its lowest level since January 2017”.
CORPORATE: Vistry Group published Trading Update
They report “Our sales rate for H1 was 1.03, similar to last year’s 1.01 and the average level of discounting from book price on private sales was 7.1% (H1 25: 1.4%)”. They also report “New land acquisition continued in Q1 but was significantly scaled back in Q2, with only limited deals on a selected number of schemes that were of high quality and in strategically important locations” and “we are reducing levels of work in progress by tightly controlling site starts and pace of build of private units on certain sites to more closely align our WIP investment to our sales rates”.
CORPORATE: Unite Group published Trading Update
They report “86% of Unite beds reserved for 2026/27 sales cycle (2025/26: 85%)”, “On track for 0-2% like-for-like income growth for 2026/27 academic year”, and “Expect 94-96% occupancy and 1-2% rental growth for 2026/27 academic year”. They also report “71% of Empiric beds reserved for 2026/27 (2025/26: 61%)”.
CORPORATE: MJ Gleeson published Trading Update
For Gleeson Homes, they report “Net reservation rates over the last six months averaged 0.80 per site per week (H2 FY2025: 0.88)” and “Excluding multi-unit agreements, net reservation rates were 0.53 per site per week (H2 FY2025: 0.64)”. They also report “The impact on build cost inflation arising from the conflict in the Middle East has been less severe than anticipated” but “we expect that inflationary pressure will continue, compounding the effect of the myriad of regulatory and tax burdens recently imposed on residential development”.
Chart of the Week
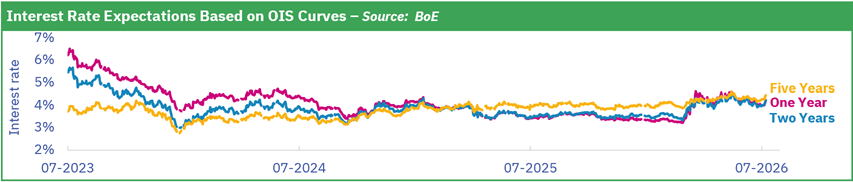
The BoE’s latest Financial Stability Report provides an update on mortgage lending at and above 4.5 times income. They report “Following the FPC’s updated Recommendation in 2025 Q2, the share of high LTI lending increased to 13.2% in 2026 Q1, up from 11.8% in 2025 Q4” and “This leaves the four-quarter rolling average at 10.8%, below the 15% limit” as per their chart below.
They also report “This increase in high LTI lending is supported by a number of factors, including strong credit supply and competition among lenders, the FCA’s clarification regarding its Mortgage Conduct of Business rules on the rates borrowers are stressed against to test affordability, and a number of lenders taking up the Prudential Regulation Authority’s (PRA’s) Modification by Consent to disapply their individual LTI flow limit”.
For context, a 4.5 times income mortgage would suggest repayments as a % of gross income of around 29% based on a 4.8% mortgage rate and 30-year term or 26% of income based on a 40-year term. Meanwhile, UK Finance reported the average repayments as % of income for first-time buyers was 21.9% in 2025, up from 16.7% in 2020.